Distribution Frequency
Gross Expense Ratio
Net Expense Ratio*
iThe Distribution Rate is the annual rate an investor would receive if the most recently declared distribution, which includes option income, remained the same going forward. The Distribution Rate is calculated by annualizing the Fund’s most recent distribution and dividing the resulting amount by the Fund’s most recent NAV. The Distribution Rate represents a single distribution from the ETF and does not represent its total return. Distributions are not guaranteed.
The Fund does not invest directly in bitcoin or any other digital assets. Investors seeking direct exposure to the price of bitcoin should consider an investment other than the Fund.
ISSB is an actively managed ETF that strives for Total Return & Income by providing approximately 1x exposure to Bitcoin and 1x exposure to large-cap U.S. stocks while generating income through a bespoke options strategy.
The performance data quoted above represents past performance. Past performance does not guarantee future results. The investment return and principal value of an investment will fluctuate so that an investor’s shares, when sold or redeemed, may be worth more or less than their original cost and current performance may be lower or higher than the performance quoted above. Performance current to the most recent month-end can be obtained by calling (844) 599-9888.
Short term performance, in particular, is not a good indication of the fund’s future performance, and an investment should not be made based solely on historical returns. Returns beyond 1 year are annualized.
A fund’s NAV is the sum of all its assets less any liabilities, divided by the number of shares outstanding. The market price is the most recent price at which the fund was traded.
ISSB is an actively managed ETF that strives for Total Return & Income by providing approximately 1x exposure to Bitcoin and 1x exposure to large-cap U.S. stocks while generating income through a bespoke options strategy.
EXPOSURE BREAKDOWN
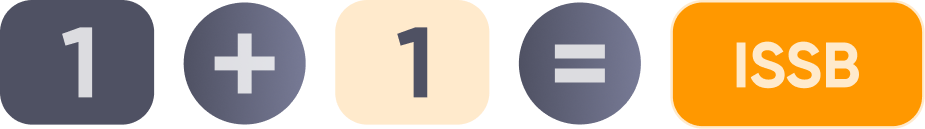
$1 = $1 Stocks + $1 Bitcoin
Exposure to large-cap U.S. stocks and Bitcoin is achieved through the purchase of call options.
Employs option premium strategies designed to collect income from market volatility. The fund may write short calls or puts, dependent on market conditions. Option premiums are an important driver of the Fund’s income potential but may also limit upside participation during strong market rallies.
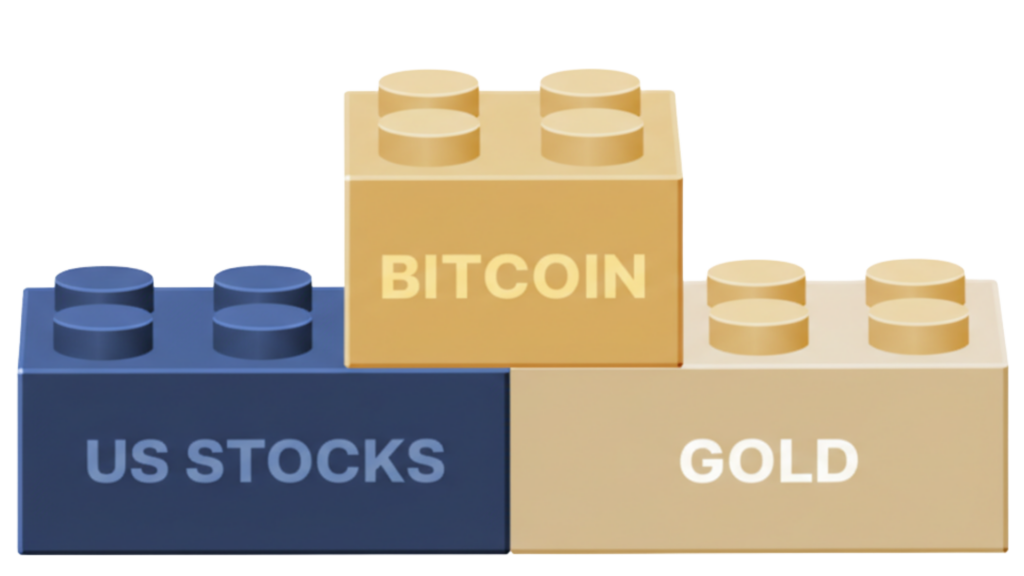
Exposure to $2 of assets for every $1 invested.
Uncapped upside participation.
Designed to keep up with — or beat — total return.
A daily active strategy that can use any options construction and harvest volatility when it's most attractive.
Only distribute what the fund can reasonably expect to generate.
Ranging from 3-18 months in tenor
Ranging 1-180 days in tenor | 0-100% of Notional
1-180 Days | 0-50% of notional
The lineup dynamically sells both calls and puts to maximize premium while minimizing risk — opportunistically. It can look like a traditional covered call fund, a 0DTE fund, or harvest very little volatility when it's unattractive.
When implied volatility sits above realized, selling options is more attractive. Implied is future volatility; realized is what was recently experienced.
Unusual or extreme skew creates opportunities to tilt the portfolio. Every asset has its own historical skew profile across strikes at a shared expiry.
The shape of the volatility curve determines whether the strategy prefers shorter or longer-dated options.
*The 30-Day SEC Yield is calculated with a standardized formula mandated by the SEC. The formula is based on the maximum offering price per share and does not reflect waivers in effect.
**The Adviser has agreed to reduce its unitary management fee to 1.14% through at least March 31, 2027. This agreement may be terminated only by, or with the consent of, the Board of Trustees (the “Board”) of Tidal Trust II (the “Trust”), on behalf of the Fund, upon sixty (60) days’ written notice to the Adviser.
**30-Day Median Spread is a calculation of Fund’s median bid-ask spread, expressed as a percentage rounded to the nearest hundredth, computed by: identifying the Fund’s national best bid and national best offer as of the end of each 10 second interval during each trading day of the last 30 calendar days; dividing the difference between each such bid and offer by the midpoint of the national best bid and national best offer; and identifying the median of those values.
Holdings are subject to change without notice.
Understanding the ISSB ETF — how it stacks equity and Bitcoin exposure, generates income, manages risk and actively harvests premium.
For every dollar invested, the strategy targets roughly 200% of exposure — 100% to equities and 100% to Bitcoin — while layering on a active options overlay to generate income, built to pursue both the potential for total return outperformance and a meaningful income stream simultaneously. The process is called return stacking, or portable alpha.
ISSB uses $0.50 of every dollar invested to achieve $1 of price exposure to both equities and Bitcoin by purchasing deep-in-the-money call options, which grant maximized price exposure with less capital. This process is called Return Stacking.
Return stacking is the use of leverage to invest in two uncorrelated or low-correlated assets simultaneously. Diversification can improve the efficiency of a portfolio by combining assets whose returns are not perfectly correlated. By stacking two 100% exposures into a single dollar of capital, an investor can access the diversification benefits of both equities and Bitcoin without having to choose between them.
Equities and Bitcoin have historically exhibited low correlation, making them a natural pairing for a stacked portfolio — Bitcoin has often served as a inflation hedge while equities have provided long-run growth.
ISSB may appeal to investors who:
Most options-income funds rely on a single, static options strategy — selling the same tenor and moneyness of calls month after month. This can signficantly cap upside capture. As markets move, the fund’s effective exposure to the underlying drifts in an uncontrolled way. ISSB flips that approach. Instead of allowing exposure to float, the goal is to keep underlying exposure at approximately 100% on each of the two assets, and dynamically sell options around that core position based on current market conditions. The fund has a fixed exposure target and a dynamic options overlay — while most competitors do the exact opposite. By fixing exposure and making the options overlay the flexible part, the strategy aims to preserve full upside participation while still harvesting volatility risk premium for income.
Consider a covered-call manager who writes calls on 50% of notional exposure. On day one, the effective delta of the combined position might be approximately 0.74 — meaning for every 1% the underlying rises, the portfolio only gains about 0.74%. If the underlying then rallies 3% over the following two weeks, the short call moves deeper in the money and the fund’s total effective exposure continues to decline. Each incremental 1% move up may only add roughly 0.58% to the covered-call strategy. This is the path-dependent math of holding a static short call alongside a long position. An active approach that targets approximately 100% underlying participation on a daily basis is designed specifically to address this structural drag.
The fund looks at three dimensions of the volatility surface to harvest volatility only when it’s attractive:
Many income products target a high headline distribution rate without regard for whether the strategy can sustainably support it. Over-distributing erodes NAV over time, ultimately degrading the compounding power of the investment. ISSB strives to distribute only what the strategy can reasonably expect to generate over a full market cycle. That discipline is intended to let both NAV and distributions compound over time — with the goal of outpacing inflation and offering full upside participation on a total-return basis.
Rather than fully replicating a synthetic long position, ISSB achieves much of its beta through in-the-money call options. A classic options identity shows that being long a call is equivalent to being long the stock plus long a put at the same strike. By accessing exposure through ITM calls, a portion of the portfolio effectively holds a long put on the same underlying. That embedded long put exposure is what can provide a degree of downside buffer during extreme drawdowns — it does not eliminate risk, but it can change how large adverse moves propagate through the portfolio. The long in-the-money call positions are also constructed using FLEX options, which allows large appreciation in the underlying to be rolled over in a tax- efficient manner.
Different assets carry meaningfully different skew profiles, and ISSB is built with those differences in mind across both of its underlying exposures:
ISSB is available on every major investment platform.